Being your own boss is one of the most empowering things you can do, and it comes with plenty of perks. You’re calling the shots, setting your own schedule, and building a business on your terms. But this also means when it comes to retirement, you’re also in charge of building your own financial future.
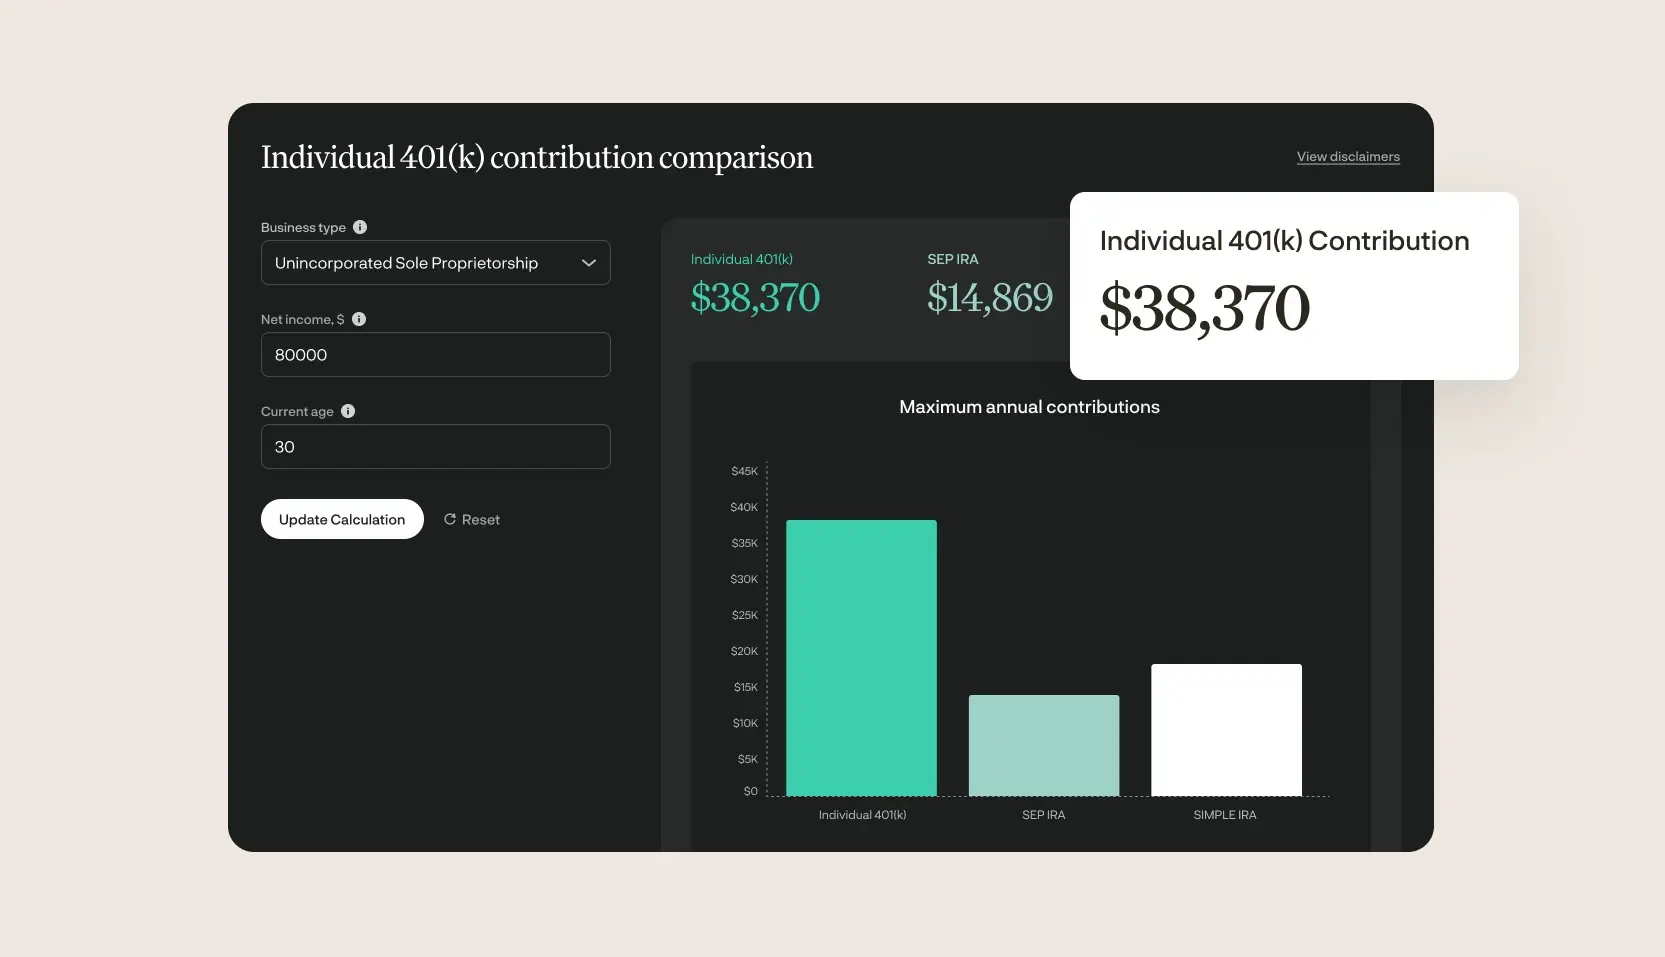
A Solo 401(k) plan comes in handy here. Designed for self-employed individuals and business owners without eligible employees other than a spouse, these plans are a great, flexible way to save for retirement while taking advantage of potential tax benefits and other money-building features.
What’s important to know is that not all Solo 401(k) plans are built the same. In fact, they often offer different fees, level of support, or features. Whether you’re a small business owner, independent contractor, or freelancer, here’s what to know about choosing the right provider for your retirement future.
What Should You Look for in a Solo 401(k) Provider?
The best Solo 401(k) provider It’s the one that offers the right balance of flexibility, support and affordability so you can focus on running your business while building a nest egg.
Here are five factors to keep in mind:
- Fees and Pricing
Some Solo 401(k) providers advertise no setup or maintenance fees, while others charge flat monthly or yearly fees. However, transaction charges, investment expenses, and asset-based fees can also impact what you pay.
Be sure to look at the total cost of the plan, which can include how your fees may change as your savings grow.
- Traditional and Roth Contributions
Traditional Solo 401(k) contributions usually have an upfront tax benefit, while Roth contributions are made with after-tax dollars and may allow for tax-free qualified withdrawals in retirement.
Not every provider supports both options, so be sure to consider which would work with your tax strategy best, Also, if you’re interested in advanced features, like Mega Backdoor Roth, confirm your chosen provider can support the feature.
- Flexible Investments
Some providers offer access to a wide range of stocks, ETFs, mutual funds, and other investments, while others are limited to a predetermined investment lineup. So, it’s important to think about how much control you want over your investments and how your strategy might change in years to come.
- Administrative and Compliance Support
Even with only one participant, there are still a number of administrative responsibilities that come with Solo 401(k) plans. Some of these include maintaining plan documents, tracking contributions, and meeting specific IRS requirements.
For example, Form 5500-EZ is generally required to be filed once a Solo plan participant’s total assets exceed $250,000 at the end of the plan year, with certain exceptions. If you need help handling this paperwork or would rather have other eyes on it, look for a provider that offers recordkeeping and compliance assistance.
- Plan Features and Flexibility
Consider the features you’ll actually use than paying extra for options you don’t need when deciding on a Solo plan. Beyond basic contributions, some Solo 401(k)s offer participant loans, rollover options, Roth conversions, and other features that can propel you towards your financial goals.
The Best Solo 401(k) Providers in 2026
Ubiquity
Ubiquity offers Solo 401(k) solutions designed for self-employed business owners who want flexibility, transparent pricing, and support with managing their retirement plans. They have two tiers of Solo plans, Single(k) and Single(k) Plus, that provide different levels of investment flexibility and recordkeeping services.
Fees
- Single(k): Starting at $19/month, billed yearly, plus a $285 one-time setup fee
- Single(k) Plus: Starting at $37.50/month, billed annually, plus a $350 one-time setup fee.
- No asset-based administration fees
Key Features
- Traditional and Roth options
- Participant loan availability
- Investment flexibility, including the ability to choose your own brokerage or custodian
- Mega Backdoor Roth option with Single(k)
- Recordkeeping services with Single(k) Plus
Pros
- Predictable flat-fee pricing
- Multiple plan options
- Access to onboarding and ongoing suppor
Considerations
Ubiquity charges setup and ongoing administration fees. Features and recordkeeping services also vary between its two Solo 401(k) plans.
Fidelity
Fidelity offers a Solo plan designed for freelancers, independent contractors, and owner-only businesses. Its plan combines broad investment options with no account opening or maintenance fees.
Fees
- No account opening or maintenance fees
- No account minimums
- Investment expenses and certain transaction fees may apply
Key Features
- Traditional and Roth contribution options
- Access to stocks, ETFs, mutual funds, and other eligible investments
- Online account opening and multiple contribution methods
- Employee and employer contribution capabilities
Pros
- Low account costs
- Broad investment options
- Access to Fidelity’s brokerage platform
Considerations
Fidelity’s standard Solo plan doesn’t permit participant loans. Business owners are also responsible for maintaining important plan records and meeting certain filing requirements.
Charles Schwab
Charles Schwab offers their Individual 401(k) plan for those who are self-employed and for owner-only businesses looking for a retirement option that’s more straightforward.
Fees
- $0 to open an account
- No maintenance fees
- Investment expenses and certain transaction fees may apply
Key Features
- Traditional and Roth contributions
- Access to stocks, ETFs, mutual funds, and other eligible investments
- Employee salary deferrals and employer profit-sharing contributions
- Brokerage and account management tools
Pros
- Low account costs
- Investment flexibility
- Access to the company’s brokerage platform
Considerations
Schwab doesn’t allow participant loans, in-plan Roth conversions, or nondeductible employee salary deferrals with their Solo plans. Employers must also manage applicable plan administration and compliance responsibilities.
E*TRADE (From Morgan Stanley)
E*TRADE from Morgan Stanley is an individual 401(k) option made for self-employed workers and their spouses. It may be especially appealing to owners who want direct control over their investments, along with access to traditional and Roth contributions.
Fees
- No standard account maintenance fees
- $0 commissions for U.S.-listed investment options
- Certain investments, transactions, and services may have additional fees
Key Features
- Traditional and Roth contribution options
- Participant loans (may be subject to plan rules)
- Access to stocks, ETFs, mutual funds, bonds, and other eligible investments
- Employee salary deferrals and employer profit-sharing contributions
Pros
- Broad investment choices
- Competitive brokerage pricing
- Access to participant loans
Considerations
Business owners are still the ones responsible for handling applicable plan administration and tax reporting. Some specialized Roth strategies may also require additional documentation and reporting.
Guideline (Now Part of Gusto)
Guideline, now part of Gusto, boasts its Solo 401(k) option as a way for self-employed individuals and owner-only businesses to simplify their contributions, investment management, and administrative responsibilities, with additional integration benefits using Gusto payroll.
Fees
Fees for a Solo plan at Guideline start at $49 per month, plus a 0.15% annual AUM fee on your balance.
Key Features
- Extra support for payroll needs
- Traditional and Roth contribution options
- S Corp compliance support
- Employer and employee profit-sharing contributions
Pros
- User-friendly digital platform
- Simplified account management
- Access to investment options made for investors who want to stay hands-off
Considerations
Investment flexibility may be more limited than with traditional brokerage providers. AUM costs can also apply depending on the amount of your assets. Business owners should also review applicable fees and available plan features to ensure they align with their retirement goals.
Human Interest
Human Interest is the final provider on our list that offers Solo 401(k) solutions to help self-employed business owners simplify retirement administration. Its platform combines digital account management, investment options, and different levels of compliance services.
Fees
- Plans start at $85 per month, plus 0.06% of your balance per month
- This added percentage comes out to 0.72% per year
Key Features
- Traditional and Roth contribution options
- Automated administration and payroll integrations
- Access to diversified investment options
Pros
- Digital retirement savings platform
- Access to investment options
- Access to tools designed to make managing a Solo plan more convenient
Considerations
Pricing and available features may vary, so self-employes business owners should confirm which services are included in their Solo 401(k) offering and whether additional fees apply. These fees can include AUM fees, which increase as your assets grow.
How Do Solo 401(k) Providers Compare?
Solo 401(k) plans offer similar core tax advantages. But while that side of things stays predictable, providers can differ significantly in investment flexibility, pricing, available features, and administrative support.
Here’s a quick look at how the seven providers we mentioned above compare:
Solo 401(k) Provider Comparison
| Provider |
Pricing Model |
Roth Option |
Administrative Support |
Notable Features |
| Ubiquity |
Flat monthly fees starting at $19, billed annually, plus setup |
Yes |
Onboarding support; recordkeeping with Single(k) Plus |
Participant loans, flexible investments, Mega Backdoor Roth option |
| Fidelity |
No account opening or maintenance fees |
Yes |
Primarily self-managed |
Online account setup, broad brokerage investments |
| Charles Schwab |
No account opening or maintenance fees |
Yes |
Primarily self-managed |
Brokerage investment options, traditional and Roth contributions |
| E*TRADE |
No standard maintenance fees; transaction fees may apply |
Yes |
Primarily self-managed |
Participant loans, broad investment options |
| Guideline (Gusto) |
Starts at $49 per month plus a 0.15% annual AUM fee |
Yes |
Digital administration and payroll integration |
Managed portfolios, automated contributions |
| Human Interest |
Starts at $85 per month, plus 0.06% of your balance per month (about 0.72% a year) |
Yes |
Tiered administration and fiduciary services |
Payroll integrations, compliance support |
How to Choose the Right Solo 401(k) Provider for Your Business
Because not all Solo plans are created equal, it’s important to be proactive and understand what each provider you’re looking into offers. Some may offer more hands-on support and flexibility, while others focus on cost-efficiency. Your best choice depends on your business, goals, and how involved you want to be with plan management.
Before choosing a provider, ask yourself:
- How much administrative support do I need? Are you comfortable and have the time to manage paperwork, tracking contributions, and handling compliance yourself? A provider can actually help with these responsibilities if you don’t want to.
- What am I actually paying? Advertised fees are just one part of the equation. Be sure to examine setup costs, ongoing administration, investment expenses, and any asset-based fees that could grow alongside your savings.
- What features matter most? Things like Roth contributions, participant loans, flexible investment options, and other features can enhance your saving strategy.
- Will my business look different in a few years? If you anticipate hiring other full-time employees beyond your spouse, you may have to convert to a traditional 401(k) plan.
- Can this provider scale and grow with my goals? The right provider will help you think beyond what you need today and have the support to back you up in the long term.
Find a Solo 401(k) That Makes Your Money Work Harder
We get it: As a business owner, you’re already wearing a lot of hats, but managing your retirement savings doesn’t have to be another full-time job. No matter if you’re a freelancer or small businesses owner, choosing the right Solo 401(k) provider can help you build a stronger financial future without adding unnecessary costs or complexity to your workload.
At Ubiquity, we design Solo 401(k) plans that work around your business by offering transparent, flat-fee pricing and plan features made to help you save more with confidence. Ready to build the right Solo 401(k) plan for your needs? Let’s find a plan that will fit with your goals.
Frequently Asked Questions
What is the best Solo 401(k) provider for self-employed individuals?
There is no one answer as the best Solo 401(k) provider depends on your retirement goals, budget, and the level of support you want. Some providers focus on low-cost, self-directed plans while others offer additional flexibility, features, and administrative assistance.
How much does a Solo 401(k) cost?
Solo 401(k) costs vary by provider. Some offer plans with no setup or yearly administration fees while others charge flat fees or additional costs for certain features and services. Investment expenses, transaction fees, or other account charges may apply.
Can I switch Solo 401(k) providers?
Yes, you can generally switch Solo plan providers if you need a different plan to better meet your needs. Depending on the provider and plan features, there may be multiple steps involved like transferring plan assets, updating plan documents, or setting up a replacement plan entirely. That’s why it’s important to review any transfer fees, administrative requirements, and tax implications so you can switch your plan smoothly.
Can I open a Solo 401(k) if I have an LLC?
Yes, you may qualify for a Solo 401(k) if they have eligible self-employment income and no eligible employees other than themselves and potentially a spouse. Both single-member and multi-member LLCs may be eligible, depending on their employees, ownership structure, and other applicable plan rules.