Everyday expenses are getting in the way of retirement savings. 57% of respondents cite financial pressures as their biggest obstacle to saving for retirement.
Employees need more than encouragement to save. 64% believe higher salaries or larger employer matches would make the biggest difference in helping employees save more.
401(k) costs and complexity remain major headaches. 39% cite plan costs and administration as their biggest retirement benefits challenge, while 34% prioritize lower or more predictable costs.
Small businesses aren’t sitting on the sidelines. 40% expanded retirement plan eligibility or employer contributions over the past year, while 37% improved employee education, communication, or participation efforts.
Like the great Jeff Goldblum once said, “Life finds a way.” But instead of dinosaurs, we’re talking about how quickly life can get in the way of saving more for retirement.
Between groceries, rising business costs, housing, and a seemingly endless list of other financial priorities, finding room in the budget for retirement savings isn’t always easy. Even more, there is an added challenge for small business owners: They need to figure out how to offer meaningful retirement benefits without stretching their resources too thin.
That’s exactly what we explored in our 2026 Small Business Retirement Index.
Our second annual survey of 2,000 respondents reveals a common theme: Both businesses and savers want to build stronger financial futures, but affordability and complexity are still getting in the way. What else is really holding retirement readiness back? Here’s everything businesses need to know and what to do about it heading into 2027.
Why Is Saving for Retirement So Challenging?
It’s hard to prioritize retirement savings when today’s financial needs are demanding your attention
In our survey, 46% of respondents identified everyday expenses as their biggest obstacle to retirement saving, while another 11% cited other financial priorities. That’s 57% struggling to balance today’s financial realities with tomorrow’s goals.
And when we ask what could help employees save more, the answers were telling:
What Could Help Employees Save More?
Respondents
Higher salaries
33%
Larger employer matches
31%
Better financial education
12%
More personalized guidance
6%
Simpler tools and technology
5%
Together, 64% believe higher pay or larger employer contributions would make the biggest difference. Another 44$ identified employer matching as the retirement plan feature they believe employees value most. Of course, not every small business can afford to increase salaries or employer contributions overnight, but that doesn’t mean there aren’t opportunities to make benefits more valuable now, and owners are already proving it.
PRO TIP: Reviewing employer matching options, improving employee education, and making it easier for workers to understand their benefits can all be meaningful steps towards stronger retirement readiness.
What Does a Small Business Retirement Plan Really Cost?
Ask yourself: Is your retirement plan really helping your business grow, or just giving you another bill to worry about? If you had to sit and wonder about this for a bit, there’s a chance that your plan may have turned into a bit of a guessing game (which we don’t want it to be!).
Our survey found that 39% of respondents cite plan costs and administration as their biggest retirement benefits challenge. And that’s not the only concern keeping employers up at night.
When choosing a retirement plan, 34% prioritize lower or more predictable costs while another 28% want simpler administration and compliance support.
But here’s where things get interesting. Among respondents whose businesses already offer a retirement plan, 38% either rarely review their plan costs or aren’t sure what they’re paying in total.
So, there’s still a lot of uncertainty around something that is supposed to help build long-term financial security.
What Should You Look for When Comparing 401(k) Costs?
Before signing up for a plan, make sure you understand what your 401(k) entails beyond than just the advertised price:
Cost or Feature
What to Consider
Administrative fees
Are fees flat, asset-based, or tied to employee count?
Investment expenses
What fees are associated with the plan’s investment options?
Administrative support
What services are included, and what costs extra?
Plan flexibility
Can you customize contributions, eligibility, and other features?
Remember: looking beyond the advertised price is key here because everything you’re paying more may not be so obvious upfront. Some plan providers charge asset-based fees that increase as plan assets grow. Others may advertise low administrative fees while charging additional fees elsewhere.
PRO TIP: Many don’t realize that if their plan isn’t meeting their needs cost-wise, they can actually transition to a different 401(k) with a different provider! If you're considering a change, our 401(k) conversion checklist can help you evaluate your options.
How Can You Keep Retirement Plan Costs Manageable?
Affordability matters but so does making sure your plan is manageable over time. But between contributions, employee eligibility, compliance requirements, and paperwork, it’s easy to see how things can get complicated.
In fact, only 40% of survey respondents feel very prepared to meet current and upcoming retirement plan requirements. Another 41% feel somewhat prepared but are still adjusting.
Managing a 401(k) can involve tracking employee eligibility, processing contributions, providing required notices and completing applicable reporting requirements.
The good news is that there are ways to make retirement plan management less overwhelming.
Start with a Retirement Plan Checkup
Whether you’re offering a 401(k) for the first time or reviewing an existing plan, consider these questions:
Are your fees predictable? Understand how your costs are calculated and whether they could increase as your plan grows.
Are administrative responsibilities manageable? Look for ways to simplify plan tasks like compliance or contributions needs.
Are employees making the most of their benefits? Consider whether better education or enrollment support could level up participation.
Is your provider keeping up with your business? The right provider will still support your workforce, payroll needs, and long-term goals as you grow.
And if the changing regulations are making your head spin, our guide to SECURE 2.0 can help you understand key requirements.
How Are Employers Improving Retirement Benefits?
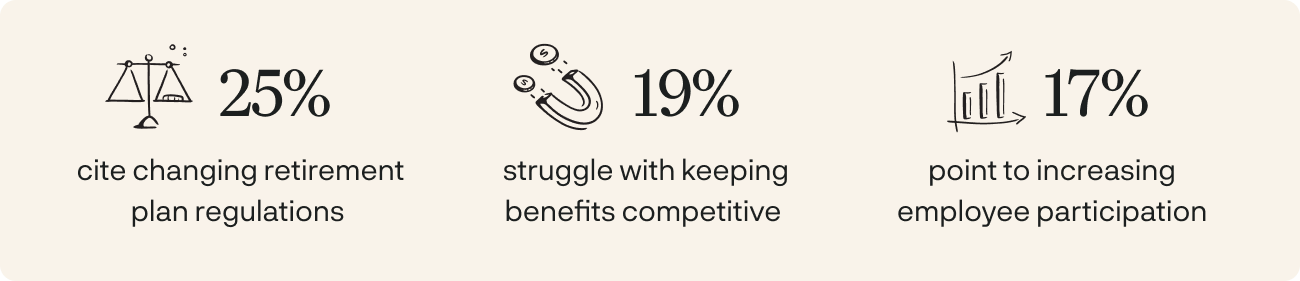
Despite financial pressures, small businesses aren't standing still. Instead of throwing in the towel, our survey found that over the past year, 40% of respondents said their businesses expanded plan eligibility or employer contributions, while another 37% reported improvements to employee education, communication or participation efforts.
And looking ahead, that momentum could continue:
44% expect their businesses to focus on improving participation, eligibility, or contributions
18% anticipate reviewing retirement plan costs or considering a new provider
So, what does this tell us? Even with tight budgets and competing priorities, employers not only recognize the important of helping their teams build financial security, but they are also taking action. They’re taking the time to revisit what is included in their plan, make changes, and optimize in small steps, leading to bigger, better improvements overall.
What Should Small Businesses Prioritize for 2027?
If there’s one thing our 2026 Retirement Readiness Index makes clear, it’s this: Small businesses want to do more for their employees, but they need retirement benefits that make financial sense.
As we move into the new year, here are three priorities to keep in mind.
Priority
What Small Businesses Can Do
Know What You’re Paying For
Review your fees, what’s included, and whether your pricing structure still makes sense as your business grows.
Make Your Retirement Benefits Work Harder
Forget the bells and whistles and focus on the features that are practical but still get you to your goals. Revisit employer contributions, eligibility rules, and plan features to make sure they still support you.
Take Complexity Off Your Plate
You have a business to run. Look for ways to simplify administration, improve payroll coordination, and get support with ongoing compliance responsibilities.
The bottom line? Retirement readiness isn’t about the having the biggest budget. You and your team can make some major strides if you make smarter decisions with the resources you have.
PRO TIP: Don’t wait until your retirement plan becomes a headache to give it a checkup. An annual review can help uncover unnecessary fees, outdated features, and administrative inefficiencies before they become bigger issues. The sooner you make identify problems and make changes, the sooner you can maximize your plan to its full potential.
How Ubiquity Helps Small Businesses Build Better Retirement Benefits
At Ubiquity Retirement + Savings, we believe small businesses shouldn’t have to choose between affordable retirement benefits and the features and support they truly need. Our retirement plans are designed to make retirement planning simpler with features like transparent, flat-fee pricing, 3(16) fiduciary services, flexible plan designs, and payroll flexibility.
Ubiquity Retirement + Savings' second annual Small Business Retirement Readiness Index is based on 2,000 completed survey responses collected in September and October 2026. The survey examined retirement plan adoption, compliance preparedness, plan costs, employee participation and personal retirement savings priorities. Findings reflect respondents' self-reported experiences and perceptions, including their views on what employees value. Percentages are rounded and may not total 100%.
recommended resource
Ubiquity’s Guide to Small Business 401(k) Plans
Tailored for small businesses, this guide helps take the complexities out of retirement planning with actionable tips and strategies, and future-thinking insights.
Like the great Jeff Goldblum once said, “Life finds a way.” But instead of dinosaurs, we’re talking about how quickly life can get in the way of saving more for retirement.
Between groceries, rising business costs, housing, and a seemingly endless list of other financial priorities, finding room in the budget for retirement savings isn’t always easy. Even more, there is an added challenge for small business owners: They need to figure out how to offer meaningful retirement benefits without stretching their resources too thin.
That’s exactly what we explored in our 2026 Small Business Retirement Index.
Our second annual survey of 2,000 respondents reveals a common theme: Both businesses and savers want to build stronger financial futures, but affordability and complexity are still getting in the way. What else is really holding retirement readiness back? Here’s everything businesses need to know and what to do about it heading into 2027.
Why Is Saving for Retirement So Challenging?
It’s hard to prioritize retirement savings when today’s financial needs are demanding your attention
In our survey, 46% of respondents identified everyday expenses as their biggest obstacle to retirement saving, while another 11% cited other financial priorities. That’s 57% struggling to balance today’s financial realities with tomorrow’s goals.
And when we ask what could help employees save more, the answers were telling:
What Could Help Employees Save More?
Respondents
Higher salaries
33%
Larger employer matches
31%
Better financial education
12%
More personalized guidance
6%
Simpler tools and technology
5%
Together, 64% believe higher pay or larger employer contributions would make the biggest difference. Another 44$ identified employer matching as the retirement plan feature they believe employees value most. Of course, not every small business can afford to increase salaries or employer contributions overnight, but that doesn’t mean there aren’t opportunities to make benefits more valuable now, and owners are already proving it.
PRO TIP: Reviewing employer matching options, improving employee education, and making it easier for workers to understand their benefits can all be meaningful steps towards stronger retirement readiness.
What Does a Small Business Retirement Plan Really Cost?
Ask yourself: Is your retirement plan really helping your business grow, or just giving you another bill to worry about? If you had to sit and wonder about this for a bit, there’s a chance that your plan may have turned into a bit of a guessing game (which we don’t want it to be!).
Our survey found that 39% of respondents cite plan costs and administration as their biggest retirement benefits challenge. And that’s not the only concern keeping employers up at night.
When choosing a retirement plan, 34% prioritize lower or more predictable costs while another 28% want simpler administration and compliance support.
But here’s where things get interesting. Among respondents whose businesses already offer a retirement plan, 38% either rarely review their plan costs or aren’t sure what they’re paying in total.
So, there’s still a lot of uncertainty around something that is supposed to help build long-term financial security.
What Should You Look for When Comparing 401(k) Costs?
Before signing up for a plan, make sure you understand what your 401(k) entails beyond than just the advertised price:
Cost or Feature
What to Consider
Administrative fees
Are fees flat, asset-based, or tied to employee count?
Investment expenses
What fees are associated with the plan’s investment options?
Administrative support
What services are included, and what costs extra?
Plan flexibility
Can you customize contributions, eligibility, and other features?
Remember: looking beyond the advertised price is key here because everything you’re paying more may not be so obvious upfront. Some plan providers charge asset-based fees that increase as plan assets grow. Others may advertise low administrative fees while charging additional fees elsewhere.
PRO TIP: Many don’t realize that if their plan isn’t meeting their needs cost-wise, they can actually transition to a different 401(k) with a different provider! If you're considering a change, our 401(k) conversion checklist can help you evaluate your options.
How Can You Keep Retirement Plan Costs Manageable?
Affordability matters but so does making sure your plan is manageable over time. But between contributions, employee eligibility, compliance requirements, and paperwork, it’s easy to see how things can get complicated.
In fact, only 40% of survey respondents feel very prepared to meet current and upcoming retirement plan requirements. Another 41% feel somewhat prepared but are still adjusting.
Managing a 401(k) can involve tracking employee eligibility, processing contributions, providing required notices and completing applicable reporting requirements.
The good news is that there are ways to make retirement plan management less overwhelming.
Start with a Retirement Plan Checkup
Whether you’re offering a 401(k) for the first time or reviewing an existing plan, consider these questions:
Are your fees predictable? Understand how your costs are calculated and whether they could increase as your plan grows.
Are administrative responsibilities manageable? Look for ways to simplify plan tasks like compliance or contributions needs.
Are employees making the most of their benefits? Consider whether better education or enrollment support could level up participation.
Is your provider keeping up with your business? The right provider will still support your workforce, payroll needs, and long-term goals as you grow.
And if the changing regulations are making your head spin, our guide to SECURE 2.0 can help you understand key requirements.
How Are Employers Improving Retirement Benefits?
Despite financial pressures, small businesses aren't standing still. Instead of throwing in the towel, our survey found that over the past year, 40% of respondents said their businesses expanded plan eligibility or employer contributions, while another 37% reported improvements to employee education, communication or participation efforts.
And looking ahead, that momentum could continue:
44% expect their businesses to focus on improving participation, eligibility, or contributions
18% anticipate reviewing retirement plan costs or considering a new provider
So, what does this tell us? Even with tight budgets and competing priorities, employers not only recognize the important of helping their teams build financial security, but they are also taking action. They’re taking the time to revisit what is included in their plan, make changes, and optimize in small steps, leading to bigger, better improvements overall.
What Should Small Businesses Prioritize for 2027?
If there’s one thing our 2026 Retirement Readiness Index makes clear, it’s this: Small businesses want to do more for their employees, but they need retirement benefits that make financial sense.
As we move into the new year, here are three priorities to keep in mind.
Priority
What Small Businesses Can Do
Know What You’re Paying For
Review your fees, what’s included, and whether your pricing structure still makes sense as your business grows.
Make Your Retirement Benefits Work Harder
Forget the bells and whistles and focus on the features that are practical but still get you to your goals. Revisit employer contributions, eligibility rules, and plan features to make sure they still support you.
Take Complexity Off Your Plate
You have a business to run. Look for ways to simplify administration, improve payroll coordination, and get support with ongoing compliance responsibilities.
The bottom line? Retirement readiness isn’t about the having the biggest budget. You and your team can make some major strides if you make smarter decisions with the resources you have.
PRO TIP: Don’t wait until your retirement plan becomes a headache to give it a checkup. An annual review can help uncover unnecessary fees, outdated features, and administrative inefficiencies before they become bigger issues. The sooner you make identify problems and make changes, the sooner you can maximize your plan to its full potential.
How Ubiquity Helps Small Businesses Build Better Retirement Benefits
At Ubiquity Retirement + Savings, we believe small businesses shouldn’t have to choose between affordable retirement benefits and the features and support they truly need. Our retirement plans are designed to make retirement planning simpler with features like transparent, flat-fee pricing, 3(16) fiduciary services, flexible plan designs, and payroll flexibility.
Ubiquity Retirement + Savings' second annual Small Business Retirement Readiness Index is based on 2,000 completed survey responses collected in September and October 2026. The survey examined retirement plan adoption, compliance preparedness, plan costs, employee participation and personal retirement savings priorities. Findings reflect respondents' self-reported experiences and perceptions, including their views on what employees value. Percentages are rounded and may not total 100%.
Watch on-demand
Enter a few of your details below to view the webinar
Thank you!
Your submission has been received! Now you can watch the webinar on-demand by clicking the button below.
Like the great Jeff Goldblum once said, “Life finds a way.” But instead of dinosaurs, we’re talking about how quickly life can get in the way of saving more for retirement.
Between groceries, rising business costs, housing, and a seemingly endless list of other financial priorities, finding room in the budget for retirement savings isn’t always easy. Even more, there is an added challenge for small business owners: They need to figure out how to offer meaningful retirement benefits without stretching their resources too thin.
That’s exactly what we explored in our 2026 Small Business Retirement Index.
Our second annual survey of 2,000 respondents reveals a common theme: Both businesses and savers want to build stronger financial futures, but affordability and complexity are still getting in the way. What else is really holding retirement readiness back? Here’s everything businesses need to know and what to do about it heading into 2027.
Why Is Saving for Retirement So Challenging?
It’s hard to prioritize retirement savings when today’s financial needs are demanding your attention
In our survey, 46% of respondents identified everyday expenses as their biggest obstacle to retirement saving, while another 11% cited other financial priorities. That’s 57% struggling to balance today’s financial realities with tomorrow’s goals.
And when we ask what could help employees save more, the answers were telling:
What Could Help Employees Save More?
Respondents
Higher salaries
33%
Larger employer matches
31%
Better financial education
12%
More personalized guidance
6%
Simpler tools and technology
5%
Together, 64% believe higher pay or larger employer contributions would make the biggest difference. Another 44$ identified employer matching as the retirement plan feature they believe employees value most. Of course, not every small business can afford to increase salaries or employer contributions overnight, but that doesn’t mean there aren’t opportunities to make benefits more valuable now, and owners are already proving it.
PRO TIP: Reviewing employer matching options, improving employee education, and making it easier for workers to understand their benefits can all be meaningful steps towards stronger retirement readiness.
What Does a Small Business Retirement Plan Really Cost?
Ask yourself: Is your retirement plan really helping your business grow, or just giving you another bill to worry about? If you had to sit and wonder about this for a bit, there’s a chance that your plan may have turned into a bit of a guessing game (which we don’t want it to be!).
Our survey found that 39% of respondents cite plan costs and administration as their biggest retirement benefits challenge. And that’s not the only concern keeping employers up at night.
When choosing a retirement plan, 34% prioritize lower or more predictable costs while another 28% want simpler administration and compliance support.
But here’s where things get interesting. Among respondents whose businesses already offer a retirement plan, 38% either rarely review their plan costs or aren’t sure what they’re paying in total.
So, there’s still a lot of uncertainty around something that is supposed to help build long-term financial security.
What Should You Look for When Comparing 401(k) Costs?
Before signing up for a plan, make sure you understand what your 401(k) entails beyond than just the advertised price:
Cost or Feature
What to Consider
Administrative fees
Are fees flat, asset-based, or tied to employee count?
Investment expenses
What fees are associated with the plan’s investment options?
Administrative support
What services are included, and what costs extra?
Plan flexibility
Can you customize contributions, eligibility, and other features?
Remember: looking beyond the advertised price is key here because everything you’re paying more may not be so obvious upfront. Some plan providers charge asset-based fees that increase as plan assets grow. Others may advertise low administrative fees while charging additional fees elsewhere.
PRO TIP: Many don’t realize that if their plan isn’t meeting their needs cost-wise, they can actually transition to a different 401(k) with a different provider! If you're considering a change, our 401(k) conversion checklist can help you evaluate your options.
How Can You Keep Retirement Plan Costs Manageable?
Affordability matters but so does making sure your plan is manageable over time. But between contributions, employee eligibility, compliance requirements, and paperwork, it’s easy to see how things can get complicated.
In fact, only 40% of survey respondents feel very prepared to meet current and upcoming retirement plan requirements. Another 41% feel somewhat prepared but are still adjusting.
Managing a 401(k) can involve tracking employee eligibility, processing contributions, providing required notices and completing applicable reporting requirements.
The good news is that there are ways to make retirement plan management less overwhelming.
Start with a Retirement Plan Checkup
Whether you’re offering a 401(k) for the first time or reviewing an existing plan, consider these questions:
Are your fees predictable? Understand how your costs are calculated and whether they could increase as your plan grows.
Are administrative responsibilities manageable? Look for ways to simplify plan tasks like compliance or contributions needs.
Are employees making the most of their benefits? Consider whether better education or enrollment support could level up participation.
Is your provider keeping up with your business? The right provider will still support your workforce, payroll needs, and long-term goals as you grow.
And if the changing regulations are making your head spin, our guide to SECURE 2.0 can help you understand key requirements.
How Are Employers Improving Retirement Benefits?
Despite financial pressures, small businesses aren't standing still. Instead of throwing in the towel, our survey found that over the past year, 40% of respondents said their businesses expanded plan eligibility or employer contributions, while another 37% reported improvements to employee education, communication or participation efforts.
And looking ahead, that momentum could continue:
44% expect their businesses to focus on improving participation, eligibility, or contributions
18% anticipate reviewing retirement plan costs or considering a new provider
So, what does this tell us? Even with tight budgets and competing priorities, employers not only recognize the important of helping their teams build financial security, but they are also taking action. They’re taking the time to revisit what is included in their plan, make changes, and optimize in small steps, leading to bigger, better improvements overall.
What Should Small Businesses Prioritize for 2027?
If there’s one thing our 2026 Retirement Readiness Index makes clear, it’s this: Small businesses want to do more for their employees, but they need retirement benefits that make financial sense.
As we move into the new year, here are three priorities to keep in mind.
Priority
What Small Businesses Can Do
Know What You’re Paying For
Review your fees, what’s included, and whether your pricing structure still makes sense as your business grows.
Make Your Retirement Benefits Work Harder
Forget the bells and whistles and focus on the features that are practical but still get you to your goals. Revisit employer contributions, eligibility rules, and plan features to make sure they still support you.
Take Complexity Off Your Plate
You have a business to run. Look for ways to simplify administration, improve payroll coordination, and get support with ongoing compliance responsibilities.
The bottom line? Retirement readiness isn’t about the having the biggest budget. You and your team can make some major strides if you make smarter decisions with the resources you have.
PRO TIP: Don’t wait until your retirement plan becomes a headache to give it a checkup. An annual review can help uncover unnecessary fees, outdated features, and administrative inefficiencies before they become bigger issues. The sooner you make identify problems and make changes, the sooner you can maximize your plan to its full potential.
How Ubiquity Helps Small Businesses Build Better Retirement Benefits
At Ubiquity Retirement + Savings, we believe small businesses shouldn’t have to choose between affordable retirement benefits and the features and support they truly need. Our retirement plans are designed to make retirement planning simpler with features like transparent, flat-fee pricing, 3(16) fiduciary services, flexible plan designs, and payroll flexibility.
Ubiquity Retirement + Savings' second annual Small Business Retirement Readiness Index is based on 2,000 completed survey responses collected in September and October 2026. The survey examined retirement plan adoption, compliance preparedness, plan costs, employee participation and personal retirement savings priorities. Findings reflect respondents' self-reported experiences and perceptions, including their views on what employees value. Percentages are rounded and may not total 100%.
Get your guide
Enter your details below to download your free PDF now
Thank you!
Your submission has been received! Now you can download the guide by clicking the button below.